
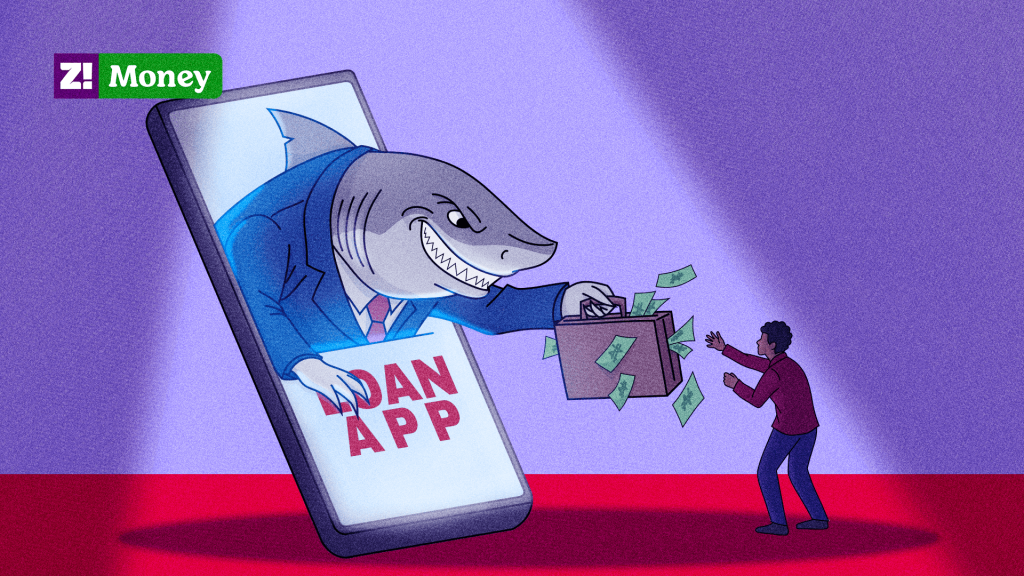
Ofure*, 40, remembers exactly how long it took to trigger a financial crisis: 10 minutes.
It was December 2024. As a single mother of three, she was staring down the barrel of a bleak festive season. Her petty trading business was capital-starved, and the When a loan app notification popped up on her phone offering instant funds, it felt like a lifeline.
鈥淚 needed 鈧�400,000 to restock for the December surge,鈥� she says, her voice quiet. 鈥淚 was convinced I鈥檇 make enough profit to repay it comfortably. The money hit my account before I could even second-guess it.鈥�
Ofure hadn鈥檛 gone to a commercial bank because they require paperwork, collateral, and the luxury of time, none of which she had. The app requested only her Biometric Verification Number (BVN), National Identity Number (NIN), and access to her contacts.
When the festive sales failed to materialise, the business collapsed. Ofure managed to meet only the first month’s repayment before hitting a financial wall. Over the remainder of the six-month window, aggressive compound interest and default penalties caused the original 鈧�400,000 principal to grow into an 鈧�800,000 burden.
In a desperate attempt to stay afloat, she began borrowing from new loan apps to service the old debt. But without any income to break the cycle, this game of borrowing from Peter to pay Paul only dug the hole deeper.
Her inability to keep up with the compounding interest caused her total debt exposure to balloon to 鈧�1.5 million over the course of a year. Today, despite struggling to make payments, nearly half of that sum remains unpaid.
Ofure is one of millions of Nigerians caught in the gravitational pull of digital lending. It is a sector that promises financial inclusion but often delivers a modern form of indentured servitude, enforced by algorithms, public shaming, and relentless psychological warfare.
The Algorithm of Harassment
The mechanics of Nigeria鈥檚 digital lending boom are built on speed, with In a country where and traditional credit is non-existent for low-income workers, fintech apps have filled the vacuum. But the ease of entry often obscures the brutality of the exit.
Many online lenders exploit financially vulnerable Nigerians through misleading loan terms, hidden charges, and aggressive recovery tactics,
鈥淚t was one of the worst decisions of my life,鈥� Ofure admits. 鈥淣ow, it feels like I’m working solely to repay the loan. The interest keeps piling up every time I miss a payment window.”
When borrowers default, the “fintech” gloss wears off, revealing a crude engine of intimidation. Ofure鈥檚 phone rings relentlessly. When she misses a payment, the threats begin. But the true weaponisation of digital lending lies in the data users unknowingly surrender.
Jalaal*, 26, an unemployed university graduate who turned to loan apps to survive, describes the moment his privacy was shattered.
鈥淚 woke up to see they had sent a broadcast message to every single person on my WhatsApp,鈥� Jalaal says. 鈥淔riends, old classmates, neighbours, even distant family. The message painted me as a chronic debtor and a fraud. For someone who tries to carry himself with dignity, the shame was unbearable.鈥�
This strategy of digitised public shaming is not an accident; it is an industrialised process.
Nneka* knows this better than anyone. She worked inside the machine, first as a telemarketer and later in the “Collections and Recovery” department of a major digital lender.
鈥淲e were given 50 to 70 contacts of delinquents every day,鈥� Nneka explains. The pressure inside the call centres is as intense as it is on the borrowers. Agents have daily recovery targets ranging from 鈧�150,000 to 鈧�240,000.
鈥淚f you don鈥檛 meet your target, they sack you fast. No grace,鈥� she says.
While company policy often officially forbids threats, the targets make them inevitable. 鈥淢ost times, Nigerian borrowers become stubborn and tell you to do your worst,鈥� Nneka notes. 鈥淭hat results in the insults. When I threaten to post a borrower鈥檚 picture to their friends, sometimes they start begging. It鈥檚 a pressure cooker.鈥�
The Regulatory Awakening
For years, this sector operated in a regulatory vacuum. Lenders were often They offered predatory interest rates, sometimes effective annual rates of over 100 per cent, masked as small monthly fees.
That was supposed to change in July 2025.
The Federal Competition and Consumer Protection Commission (FCCPC) unveiled the . It was billed as a mandatory framework replacing the patchwork interim rules of 2022.
鈥淭he borrower was often treated like a slave to the lender,鈥� 鈥淲e had situations where an app would pop up, entice you, and the next moment, you are defamed and harassed. The DEON regulation is a blueprint to stop that.鈥�
The new rules, on paper, appear stringent. They require:
- Mandatory Registration: Every digital lender must register, revealing the humans behind the corporate veil.
- Suitability Assessments: Lenders are legally required to verify that a borrower can afford to repay, thereby ending the practice of lending to desperate individuals without proper consideration.
- Data Sanctity: A strict ban on accessing contacts, photos, or using shaming tactics.
鈥淚n the past, operators never bothered to check if consumers could pay back,鈥� Ijagwu notes. 鈥淣ow, not doing so is an offence. We can hold individual operators and corporate organisations responsible. The penalties are severe, with up to 鈧�100 million or a suspension of operations.鈥�
The Gap Between Law and Reality
However, three months into this new regulatory regime, the gap between the law and the people remains wide.
a Data Protection and Privacy Expert, argues that the violation is by design: “The apps are built to strip-mine a user’s phone, seizing access to private data purely to gain leverage over the borrower. A bank doesn’t ask for your entire contact list,鈥� Olawuyi says. 鈥淭he fact that these apps do is already a violation of the principle of 鈥楧ata Minimisation鈥� under the They collect information for 鈥榞uarantors鈥� but use it for intimidation.鈥�
While the DEON regulations and the Nigeria Data Protection Commission (NDPC) provide a pathway for recourse, access to justice is unequally distributed.
鈥淭he NDPC has made complaint channels available and translated the Act into Igbo, Hausa, and Yoruba,鈥� Olawuyi acknowledges. 鈥淏ut does the average woman on the street, the primary target of these loans, know that? When a loan agent calls to threaten, does she know that it is a reportable offence, or does she just feel shame?鈥�
, a consumer protection lawyer, agrees that awareness is the missing link.
鈥淢ost consumers try to keep things quiet,鈥� Bantale says. 鈥淭hey are reluctant to seek help because they feel they are in the wrong for owing money. This silence allows for exploitation. Although the law requires lenders to assess repayment capacity, many lenders bypass this requirement. And truthfully, borrowers sometimes provide wrong information just to get the cash.鈥�
Feeding the Addiction
The country鈥檚 high cost of living does not solely drive the crisis. The frictionless nature of digital loans has also weaponised addiction.
Ayodeji*, 28, a young professional earning 鈧�500,000 a month, , didn鈥檛 borrow to survive inflation. He borrowed to fuel a gambling habit.
鈥淚n 2024, I borrowed up to 鈧�1 million from 20 different loan apps to fuel my addiction,鈥� Ayodeji says. 鈥淚 borrowed as much as I wanted, and didn鈥檛 pay all of them back.鈥�
For Ayodeji, the shaming tactics lost their power through sheer volume. 鈥淭hey always called and texted, threatening to post my obituary. I just repaid the ones I felt like paying and deleted the apps. Their threats didn鈥檛 scare me at all.鈥�
If a borrower can cycle through 20 different apps, leveraging one to pay another or to fund a betting spree, it proves that the systems central to a healthy financial market are evidently failing to flag high-risk behaviour in real-time.
A Long Road to Recovery
The DEON 2025 regulations have undoubtedly raised the barrier to entry for digital lenders. The days of are numbered, as the FCCPC now demands to know exactly who is pulling the strings.
But for Ofure, these high-level policy shifts feel abstract. She is still receiving threatening calls today, months after the regulations took effect.
鈥淚鈥檓 not even aware of any new digital lending rules,鈥� she says wearily. 鈥淭he pressure and harassment haven鈥檛 changed. When I make a late payment, I still get pressured.鈥�
To keep the agents at bay, Ofure added her teenage son鈥檚 number as her secondary contact鈥攁 decision she regrets deeply. 鈥淭hey called and sent vile messages to him. I loathed myself for dragging him into this. It was devastating.鈥�
The tragedy of the digital lending trap is that it works until it doesn’t. It provides liquidity at the speed of light, but extracts value at the speed of compound interest.
鈥淣o one envisages such things happening,鈥� Ofure says, 鈥淏efore you collect that kind of money, you have hope that you鈥檒l pay back. You have hope.鈥�
For now, that hope is the only currency she has left.
鈥淚鈥檓 not worrying myself anymore,鈥� she concludes, a note of resignation in her voice. 鈥淲henever I get money, I鈥檒l pay. If I don鈥檛 have it, there鈥檚 nothing I can do. As long as I鈥檓 still alive, there鈥檚 hope.鈥�
KNOW YOUR RIGHTS: The DEON 2025 Borrower鈥檚 Guide
The Digital, Electronic, Online or Non-Traditional Consumer Lending Regulations (have rewritten the rules of engagement. If you are taking a digital loan, these are your non-negotiable rights:
1. The Right to Privacy: This strictly prohibits lenders from accessing your contact list, photo gallery, or social media accounts. They cannot contact your friends, family, or employer to shame you into repayment. If an agent messages your contacts, they are breaking the law.
2. The Right to Full Disclosure: No more hidden fees. Before you click “Accept,” the lender must display a Key Facts Statement that shows the full cost of the loan, including the interest rate, total repayment amount, late fees, and the tenor, in plain English.
3. The Right to a Suitability Assessment: Lenders can no longer throw money at you if you cannot afford it. They are legally required to assess your ability to repay the loan before granting it. If they give you a loan without checking your income or creditworthiness, they are liable for reckless lending.
4. The Right to Fair Recovery: Harassment is illegal. Lenders must conduct debt collection ethically and within reasonable hours (8 AM 鈥� 8 PM). Threats of arrest, physical harm, or the creation of “wanted” posters are criminal offences under the new framework.
5. The Right to Redress: If a lender violates these rules, you have the right to report them directly to the FCCPC. The regulator now has the power to suspend the lender’s license and impose fines of up to 鈧�100 million.
To report a violation: or contact their dedicated digital lending task force.
*Names have been changed to protect the identity of the subjects.
Next Read: 鈥淓veryone Thinks I Owe Them Something鈥�: The Economics of Nigerian Entitlement
for relatable stories and actionable insights to help you make the most out of your money.